Beyond the Mortgage: What HOA Fees and Community Assessments Actually Cost Central Pennsylvania Homebuyers
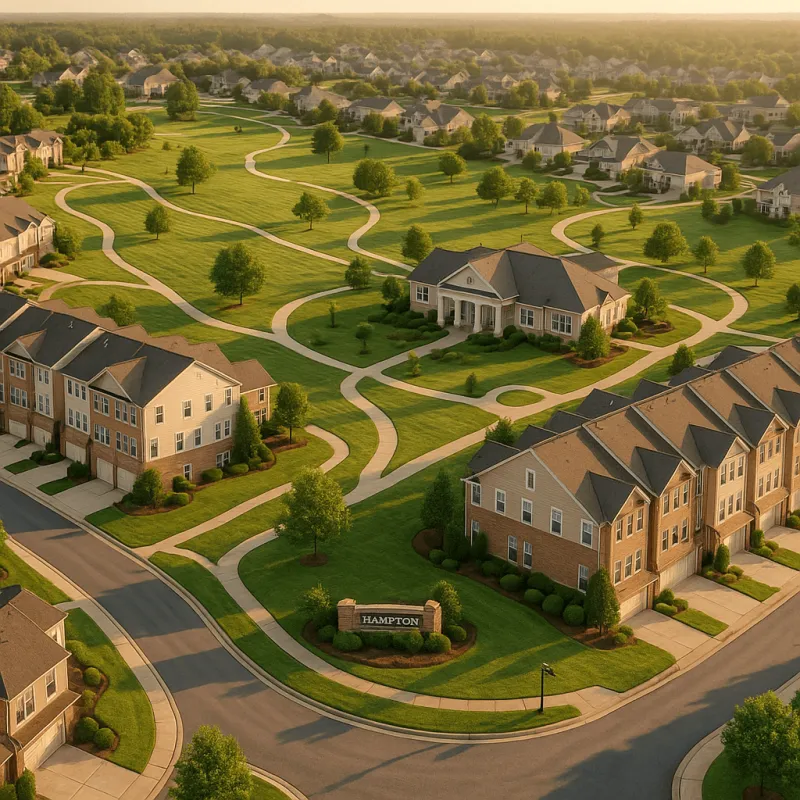
Photo: homeowners association planned community neighborhood Pennsylvania suburban development, via communityfirstpm.com
For many buyers touring Central Pennsylvania's newer planned communities—from the growing subdivisions outside Harrisburg to the master-planned neighborhoods near State College and York—the appeal is immediate. Fresh construction, maintained common areas, uniform landscaping, and community amenities like pools, walking trails, and clubhouses create an undeniable sense of order and lifestyle. What is less immediately visible is the financial layer that sustains all of it.
Homeowners association fees and the ancillary charges that accompany them represent one of the most consistently underestimated costs in residential real estate. Buyers who carefully compare mortgage rates and negotiate on purchase price sometimes sign closing documents without fully understanding that their monthly housing obligation extends well beyond principal, interest, taxes, and insurance. In Central Pennsylvania's expanding development corridors, that oversight can prove costly.
What HOA Fees Actually Cover—and What They Don't
At their most basic level, HOA fees fund the maintenance of shared spaces and community infrastructure. In Central Pennsylvania developments, this typically includes lawn care for common areas, snow removal from private roads and sidewalks, exterior maintenance for attached or condominium-style units, and upkeep of amenity facilities.
The range is considerable. Smaller, lower-amenity subdivisions in Cumberland or Dauphin County may carry monthly fees between $75 and $150. Larger communities with premium amenities—gated access, fitness centers, resort-style pools, or on-site management staff—can run $300 to $600 or more per month. Townhome and condominium communities often sit at the higher end of this range because the HOA assumes responsibility for exterior building components that single-family homeowners manage independently.
What fees do not always cover is equally important to understand. Buyers frequently assume that a robust monthly payment protects them from additional financial exposure. In practice, HOA fees fund routine operating expenses, while capital improvements, emergency repairs, and infrastructure replacements draw from a separate reserve fund—or, when reserves are inadequate, from the homeowners themselves.
The Reserve Fund: The Number Most Buyers Never Ask About
Perhaps no single figure in an HOA's financial documents matters more than its reserve fund balance and the corresponding reserve study. A reserve study is a professional assessment of the community's long-term capital needs—roofing replacement on common structures, repaving of private roads, pool resurfacing, elevator systems in multi-story buildings—and the funds required to address them on a projected timeline.
A well-funded reserve typically holds 70 percent or more of the projected replacement cost for major components. Communities that fall below this threshold are considered underfunded, and the financial gap must eventually be closed. In Central Pennsylvania, as in other regions where rapid residential development has outpaced long-term financial planning, underfunded reserves are not uncommon in communities less than a decade old.
Buyers should request the most recent reserve study and the HOA's current reserve fund balance before making any purchase decision in a planned community. If the association lacks a current study or declines to provide documentation, treat that as a significant warning.
Special Assessments: The Expense Nobody Budgets For
When reserve funds prove insufficient for a necessary capital expenditure, HOAs have the authority to levy special assessments against all homeowners. These are one-time or periodic charges that fall outside of regular monthly dues, and they can be substantial.
Examples from communities across Central Pennsylvania illustrate the range of exposure. A community in the Mechanicsburg area assessed each homeowner approximately $2,800 over two years to fund road repaving after the reserve fund balance proved inadequate. A townhome community near Lancaster levied a $1,500 per-unit assessment for structural repairs to shared retaining walls. In some cases, special assessments have exceeded $10,000 per household for major infrastructure projects.
Unlike mortgage payments, special assessments rarely come with advance notice or extended repayment terms. Some HOA governing documents permit installment plans, but many require lump-sum payment within 30 to 90 days of the assessment notice. Buyers who do not account for this contingency in their financial planning may find themselves in a difficult position.
Reading the Governing Documents: What to Scrutinize
Every HOA is governed by a set of legal documents—commonly the Declaration of Covenants, Conditions, and Restrictions (CC&Rs), the bylaws, and the rules and regulations. Pennsylvania law entitles prospective buyers to review these documents prior to closing, and doing so is not optional if you intend to make a genuinely informed decision.
Specific provisions deserve careful attention:
Assessment authority and caps. Some governing documents limit how much the HOA board can increase regular dues annually without a homeowner vote—often 5 to 10 percent. Others impose no such restriction. Understanding whether your future HOA operates under a cap is material to your long-term budget.
Special assessment thresholds. Review whether the board can levy special assessments unilaterally or whether homeowner approval is required above a certain dollar amount. This provision significantly affects your financial exposure.
Mandatory amenity fees. Some Central Pennsylvania communities include mandatory membership fees for specific amenities—golf courses, marinas, or private recreation facilities—that are billed separately from standard HOA dues. These charges may not be prominently disclosed during the sales process.
Rental and resale restrictions. Certain communities limit your ability to lease the property or impose right-of-first-refusal provisions on resale. These restrictions affect both your flexibility as an owner and the property's future marketability.
Litigation history. Meeting minutes and financial disclosures may reveal ongoing or recent litigation involving the HOA, which can signal governance problems, deferred maintenance disputes, or construction defect claims—all of which carry financial implications for current owners.
Comparing Costs Across Central Pennsylvania Communities
When evaluating multiple properties that include HOA obligations, a direct comparison requires standardizing the full monthly cost of ownership. A home priced $20,000 lower than a comparable property may carry HOA fees $175 per month higher, erasing the apparent value advantage over a standard holding period.
Buyers should also consider what the fee structure actually delivers relative to what they would spend independently. A community with a $200 monthly fee that includes lawn maintenance, snow removal, and exterior painting may represent genuine savings for a buyer who would otherwise hire those services. A community charging the same amount for amenities the buyer will not use offers no comparable offset.
Working with a buyer's agent who is familiar with Central Pennsylvania's planned communities can help provide context on how specific HOA fees compare to regional norms and whether a community's financial health appears sound based on publicly available records.
Making the Decision with Full Information
Planned communities throughout Central Pennsylvania offer real lifestyle benefits, and for many buyers, the structure and amenities they provide justify the associated costs. The objective is not to discourage consideration of HOA communities but to ensure that every buyer enters the transaction with an accurate picture of total cost of ownership.
Request governing documents early in the process. Review the reserve study and current fund balance. Ask about any pending or anticipated special assessments. Confirm whether any mandatory fees exist beyond standard dues. And evaluate the HOA's financial statements with the same diligence you would apply to the property inspection report.
The asking price on a listing is a starting point. For homes in Central Pennsylvania's planned communities, the full financial commitment is a more complete—and consequential—number.